PHOTO
Narrandera Shire Council has formally endorsed an obligation on banks to fund face-to-face banking in regional Australia campaign led by the Regional Banking Investment Alliance and the inclusion of the Narrandera Shire Council logo on RBIA materials.
The council has advocated to the commonwealth government to legislate a cost sharing model for banks to fund regional face-to-face banking services and will continue to leverage council’s existing advocacy platforms to amplify the campaign.
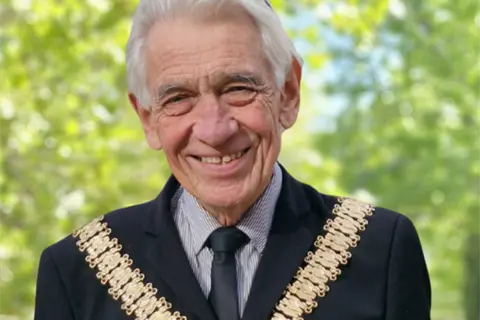
“Since 2017, over 870 bank branches have closed in regional and remote Australia. Despite numerous inquiries and recommendations, including the appointment of a Regional Banking Taskforce, there is currently no support to help regional banks provide essential services to people in regional, rural and remote communities,” Narrandera mayor Neville Kschenka said.
“Small regional banks are increasingly being used as de facto branches for the majors in a process known as ‘pass-through banking’. These small banks carry the costs of providing face-to-face banking services but receive none of the commercial benefits, with home loans and deposits being held by larger or digital banks.
“Regional banks are also subject to higher costs for cash-in-transit services due to their location.”
Mayor Kschenka said a moratorium on regional bank closures, announced in 2025 by the treasurer and the ‘Big Four’ banks, is set to expire in 2027.
“The moratorium does not affect any other banks, nor does it apply to opening hours. Bank@Post offers very limited services compared to a bank branch with properly trained staff.
“In 2024, treasury began proposing the concept of a community service obligation on banks. The Regional Banking Investment is made up of 24 regional banks and a number of supporter organisations.
“They have taken treasury’s proposal and developed it into a community service obligation (CSO) cost sharing model for banks. The model would be used to provide a direct contribution to any bank which maintains or expands regional bank branches.
“It would ensure ongoing support to preserve the financial viability of existing branches and incentivise banks to invest in new ones.”
Mayor Kschenka said the model was 100 per cent funded by banks with no taxpayer funds required.
The model would be used to help fund trained staff in work in face-to-face banking roles in regional and remote Australia.
It would apply only to banks that provide trained face-to-face core retail banking services, including cash management.
The CSO would cover about 32 per cent of the average cost of running a regional bank branch, equivalent to three full-time equivalent (FTE) staff.
Across the industry this would amount to around $153 million, or 0.17 per cent of the total operating income of the major banks.
“The advantage of an FTE base for a subsidy is that it scales according to the level of service provided. If a bank branch is open for five days of the week, then it is providing a better service than one opening just three days – all else being equal. FTE numbers will reflect this longer opening time,” he said.
It is also proposed that the base FTE costs are adjusted annually by a suitable wage price index. Other essential services in Australia are legislated in a similar way to the Community Service Obligation proposed by the Regional Banking Investment Alliance.
A Universal Service Obligation already exists in telecommunications to ensure that standard telephone services and public payphones are made reasonably accessible to all Australians on an equitable basis, requiring the primary universal service provider.
A Community Service Obligation funding pool was established by the federal government in 2006 to ensure that arrangements are in place to provide all Australians with ongoing and timely access to all PBS medicines, through community pharmacies.
The Risk Equalisation (RE) Scheme is a financial transfer mechanism administered by the Australian Prudential Regulation Authority (APRA) under the Private Health Insurance Act 2007.
It operates as a zero-sum pool, redistributing money among private health insurers (PHIs) to support the sustainability and fairness of Australia’s private health insurance system.
When a local bank branch closes, customers are compelled to travel elsewhere for their banking needs, reducing foot traffic and transactions at other local shops and businesses. While this shift may benefit larger regional centres, it negatively impacts smaller ones.
Another significant issue arising from increased travel distances and reduced access to banking services is the heightened financial and physical risk associated with individuals and businesses needing to retain larger cash holdings for extended periods.
Given there is a cash mandate on grocery and fuel retailers, security risks become even greater for these business types when local branches are closed.
Community support
Many community groups rely on their local banks for sponsorships and support for local events, sporting groups and community projects. Local banks are part of their local communities and want to contribute to the prosperity of the community in which they live.
Employment
Local bank branches provide flexible, skilled jobs in regional and remote communities encouraging young people to stay in their local community and attracting new families to regional towns
Local context
Local bank branches understand their community, its economics and the people in it. This understanding is added to metrics to help inform and work with members of their community. This can also aid in detecting financial abuse, scams and fraud.
Digital disadvantage, outages and natural disasters
Rates of digital exclusion are higher in regional areas, as are outages and spotty network coverage. Regional areas also suffer from more natural disasters. Face-to-face cash services are a necessity for these communities.
Conclusion
The banking system provides essential services that underpin a market-based economy, and these services must be universally accessible. Regional communities contribute to Australia’s prosperity, and the highly profitable banks who owe their success to regional communities should be obligated to service them.
Supporting the Obligation on banks to fund face-to-face banking in regional Australia acknowledges the importance of face-to-face banking services as part of the main street businesses in towns throughout the country.
If regional Australia is expected to grow, produce and sustain, then face-to-face banking services need to be maintained and supporting this campaign puts that expectation where it belongs, on the banks themselves.